
Key Takeaways
- • Dated Bitcoin futures volume on offshore venues has collapsed 97% from 2021 peak levels, signaling a structural shift in how institutional traders manage directional risk and leverage in crypto derivatives markets.
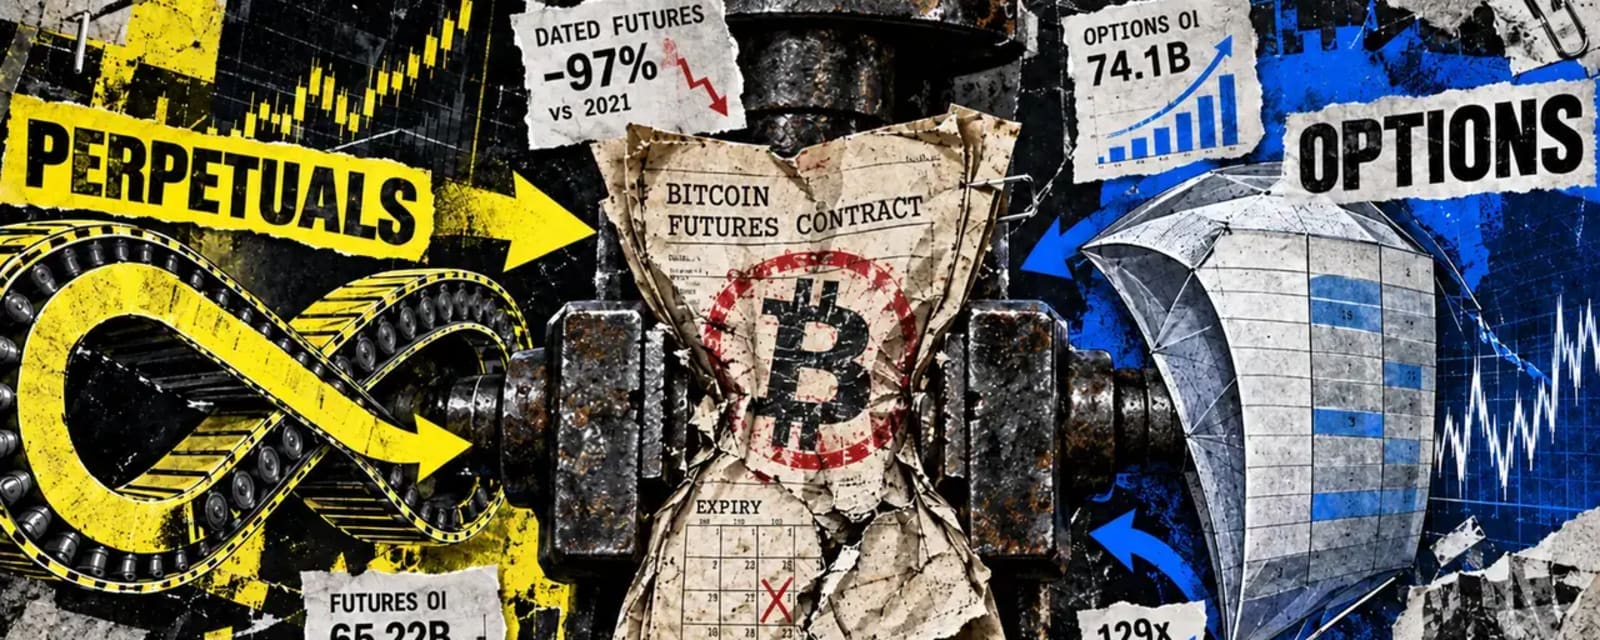
- • Options contracts have expanded to represent nearly 50% of Bitcoin derivatives open interest, compared to roughly 25% five years ago, with the options-to-futures ratio flipping in January 2026 when Bitcoin options reached $74.1 billion against $65.22 billion in futures.
- • Perpetual futures have absorbed directional trading demand previously served by dated futures, offering leveraged exposure without expiry management concerns, while options have captured hedging, volatility, and downside protection strategies.
- • The market restructuring reflects institutional sophistication and risk fragmentation, with traders now allocating to products better suited to specific risk profiles rather than concentrating activity in traditional expiry-based futures contracts.
Summary
Bitcoin's derivatives market has undergone a fundamental structural transformation over the past five years, despite growing institutional participation and market sophistication. While the overall derivatives ecosystem has expanded significantly with more advanced products and larger institutional involvement, one of its foundational instruments—dated futures on offshore crypto-native venues—has nearly vanished from the market. According to Glassnode data cited by CryptoSlate, dated futures volume across tracked offshore venues now sits approximately 97% below its 2021 level, representing a dramatic retreat from what was once a core market instrument.
This collapse has not reflected a contraction in derivatives activity but rather a fundamental reallocation of trading flows toward alternative products. Options contracts have emerged as the primary beneficiary, expanding from roughly one-quarter of crypto-native Bitcoin derivatives open interest in 2019 to nearly 50% by 2026. CryptoSlate's market analysis documented this shift across multiple regimes, noting that options gained share during four of five market cycles studied since 2019. The inflection point occurred in January 2026, when Bitcoin options open interest surpassed futures for the first time in the firm's tracking history, reaching approximately $74.1 billion compared to $65.22 billion in futures contracts.
The structural shift reflects a rational bifurcation of the derivatives market based on risk management utility. Perpetual futures contracts—which carry no expiration date—have become the preferred vehicle for leveraged directional trading, eliminating the operational burden of rolling positions or managing expiry mechanics. Options contracts, meanwhile, have captured demand for volatility trading, hedging strategies, downside protection structures, and trades predicated on specific price levels or time horizons. This division has left traditional dated futures squeezed between two specialized products, each optimized for distinct use cases that dated futures served less effectively than their alternatives.
The migration signals maturation in how institutional and professional traders approach crypto risk management. Rather than concentrating leverage and directional bets in a single product category, market participants now deploy capital across instruments specifically engineered for their strategic objectives. This granularization of risk represents a departure from crypto derivatives' earlier structure, where dated futures dominated market activity, toward a more segmented and sophisticated institutional framework typical of mature derivatives ecosystems in traditional finance.
Go deeper than the headline
Research every firm in this story, track the ones that matter and get the daily briefing — free for 7 days.