
Key Takeaways
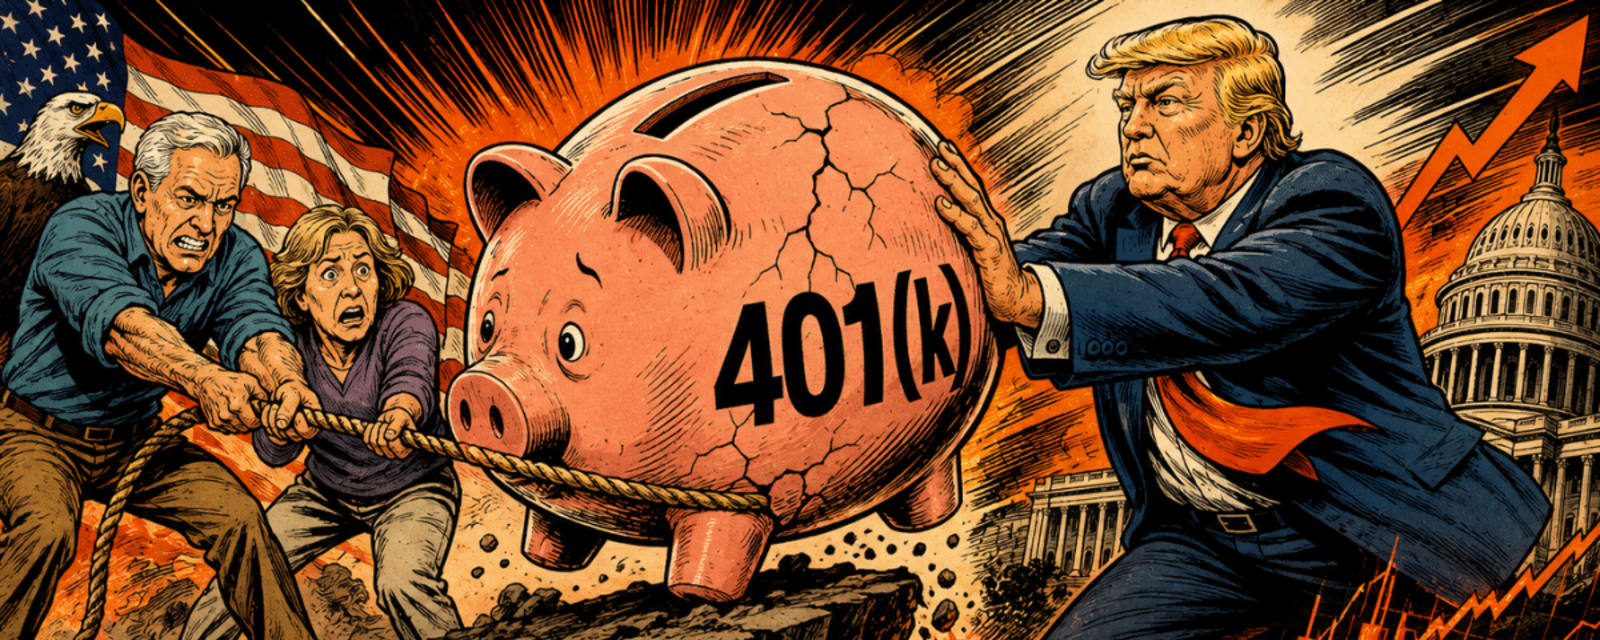
- • Trump administration has signed an executive order permitting cryptocurrencies and private equity to be included as investment options within 401(k) retirement plans, opening these traditionally conservative vehicles to higher-risk alternative assets.
- • A significant public sentiment gap exists: 77% of US adults view the addition of cryptocurrency to workplace retirement plans as risky, indicating widespread concern among retail investors about exposure to volatile digital assets within retirement savings.
- • The policy change eliminates previous regulatory barriers imposed by the Labor Department, which historically restricted 401(k) plans from allocating capital into speculative and less-regulated investment categories to protect retirement savers.
- • The initiative reflects a strategic effort to expand cryptocurrency and alternative asset adoption at scale, leveraging the $11+ trillion 401(k) market as a potential entry point for institutional and retail participation in crypto and private equity.
- • Financial professionals and institutional investors face heightened due diligence requirements and potential fiduciary liability concerns as 401(k) plan sponsors and administrators navigate new permissible asset classes with limited regulatory guardrails.
Summary
The Trump administration has moved to fundamentally alter the composition of 401(k) retirement plans by signing an executive order that permits the inclusion of cryptocurrencies and private equity as allowable investment options. This represents a significant departure from decades of Labor Department policy designed to restrict 401(k) allocations to more stable, regulated securities and traditional assets. The order effectively opens the regulatory door for plan sponsors to offer crypto and private equity products within employer-sponsored retirement vehicles.
Public reception to this policy shift reveals a pronounced disconnect between administrative objectives and investor sentiment. According to available polling data, nearly 77% of US adults perceive the inclusion of cryptocurrency in workplace retirement plans as constituting excessive risk. This substantial majority concern underscores the potential political and regulatory challenges ahead, as retirement security remains a politically sensitive issue affecting broad swaths of the electorate. The public perception data suggests meaningful headwinds to adoption despite the administrative green light.
The policy removes previous regulatory constraints that the Labor Department had maintained to protect retirement savers from exposure to illiquid, volatile, and less-transparent alternative assets. By broadening permissible investment categories, the order theoretically allows individual investors with 401(k) plans to allocate portions of their retirement savings—in some proposals mentioned at 1% allocation levels—into cryptocurrency and private equity holdings. This shift materializes within a 401(k) market exceeding $11 trillion in total assets.
For institutional investors, hedge fund managers, and family offices that may serve as custodians or investment managers for these plans, the regulatory environment now presents both opportunities and compliance uncertainties. Plan sponsors will face heightened scrutiny regarding fiduciary duty obligations when offering crypto and private equity options to employees, particularly given widespread public skepticism about risk appropriateness. Financial professionals managing these vehicles must establish robust documentation, risk disclosure frameworks, and investment policies that address the novel asset classes now permitted within tax-advantaged retirement accounts.
Public reception to this policy shift reveals a pronounced disconnect between administrative objectives and investor sentiment. According to available polling data, nearly 77% of US adults perceive the inclusion of cryptocurrency in workplace retirement plans as constituting excessive risk. This substantial majority concern underscores the potential political and regulatory challenges ahead, as retirement security remains a politically sensitive issue affecting broad swaths of the electorate. The public perception data suggests meaningful headwinds to adoption despite the administrative green light.
The policy removes previous regulatory constraints that the Labor Department had maintained to protect retirement savers from exposure to illiquid, volatile, and less-transparent alternative assets. By broadening permissible investment categories, the order theoretically allows individual investors with 401(k) plans to allocate portions of their retirement savings—in some proposals mentioned at 1% allocation levels—into cryptocurrency and private equity holdings. This shift materializes within a 401(k) market exceeding $11 trillion in total assets.
For institutional investors, hedge fund managers, and family offices that may serve as custodians or investment managers for these plans, the regulatory environment now presents both opportunities and compliance uncertainties. Plan sponsors will face heightened scrutiny regarding fiduciary duty obligations when offering crypto and private equity options to employees, particularly given widespread public skepticism about risk appropriateness. Financial professionals managing these vehicles must establish robust documentation, risk disclosure frameworks, and investment policies that address the novel asset classes now permitted within tax-advantaged retirement accounts.
Go deeper than the headline
Research every firm in this story, track the ones that matter and get the daily briefing — free for 7 days.