
Key Takeaways
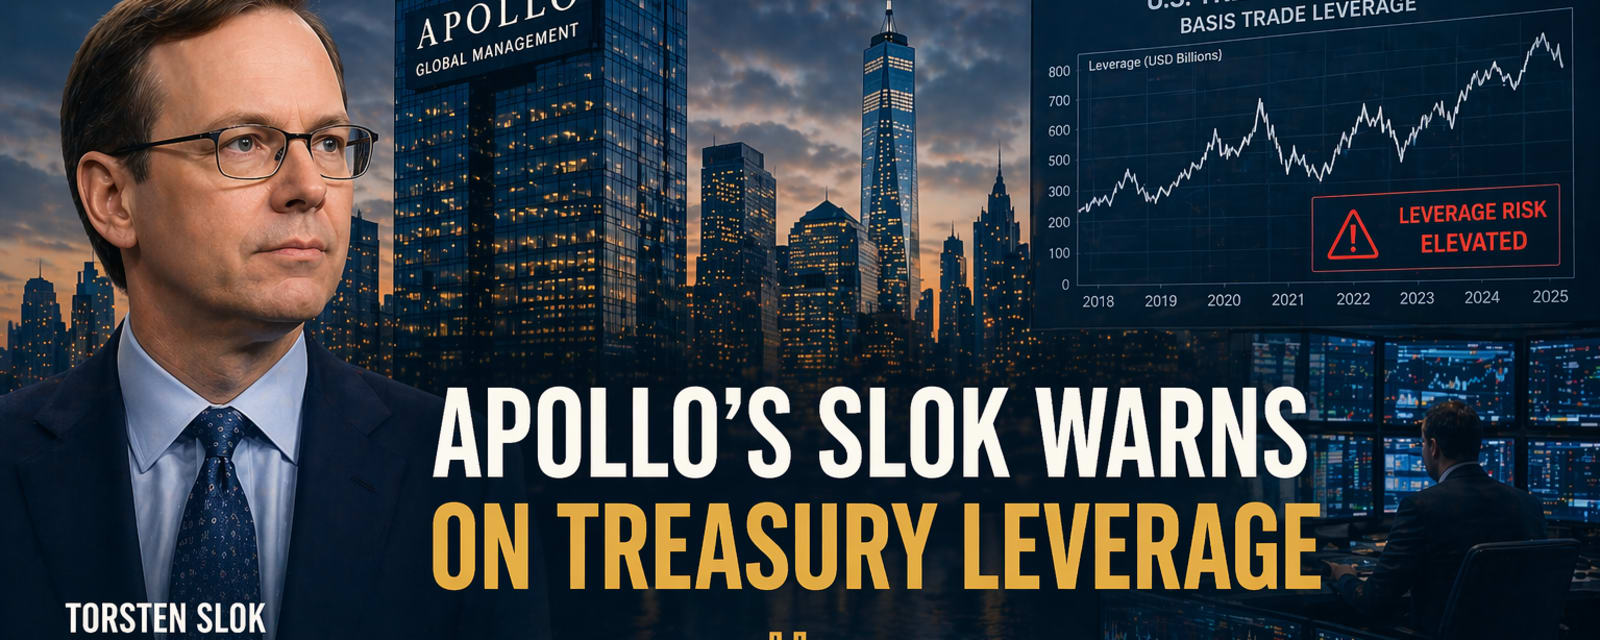
- • Torsten Slok, chief economist at Apollo Global Management, has issued a client warning regarding elevated leverage in the U.S. Treasury market centered on the "basis trade" strategy, flagging systemic risk potential during a period of heightened earnings-season volatility.
- • The Treasury basis trade—a relative-value arbitrage strategy that exploits price spreads between cash Treasuries and Treasury futures—has grown to hundreds of billions of dollars in notional size, making it one of the largest and least visible leverage sources in the financial system.
- • Hedge funds execute basis trades by financing the cash leg through the repurchase (repo) market, amplifying returns through borrowed capital; this structural dependency on repo funding creates vulnerability to sudden deleveraging cascades.
- • A forced unwinding of leveraged Treasury positions could trigger market stress extending far beyond fixed income markets, presenting systemic contagion risks at a critical moment when institutional portfolios are already navigating earnings-season volatility.
Summary
Torsten Slok's warning, circulated to Apollo Global Management clients, underscores an emerging vulnerability in fixed income markets that has largely escaped mainstream regulatory scrutiny. The basis trade—a market-neutral arbitrage strategy that simultaneously buys cash Treasury bonds while selling Treasury futures contracts—has expanded dramatically in scale over recent years. While individual basis trades capture modest spread opportunities, the aggregate leverage embedded across the hedge fund complex now represents a material systemic risk factor.
The mechanics of the basis trade are straightforward in principle but carry outsized implications when leveraged. Traders exploit the pricing discrepancy between physical Treasury bonds and Treasury futures, financing the cash purchase leg through repo borrowing. This structure allows hedge funds to amplify returns on modest basis point differentials, but creates a dual dependency: both on the persistence of the spread and on continued access to cheap repo funding. Market participants estimate hundreds of billions of dollars are currently deployed in basis trade strategies across the industry.
Slok's timing carries particular weight given the current market environment. Earnings season—characterized as the "Super Bowl of Earnings" by trading desks—is historically a period of elevated volatility and rapid portfolio rebalancing. If market conditions deteriorate sharply or repo funding becomes constrained, forced deleveraging of basis positions could initiate a cascading unwinding. The systemic concern is not confined to Treasury markets; the interconnectedness of leveraged positions across hedge funds creates contagion pathways into equity, credit, and derivatives markets. The re-emergence of basis trade risk warnings reflects institutional memory of past volatility episodes where seemingly isolated relative-value trades became flashpoints for broader market stress.
Go deeper than the headline
Research every firm in this story, track the ones that matter and get the daily briefing — free for 7 days.