
Key Takeaways
- • Default risk and market stress replaced negative market perception as the top challenge facing private credit over the next six months, according to PitchBook LCD's Q3 Global Private Credit Survey, conducted Oct. 7-19 among lenders, banks, PE firms and advisers in the US and Europe.
- • Non-traded BDC net flows turned negative for the first time in the dataset's history in Q2 2026, and a plurality of respondents viewed the outflows as a temporary setback tied to AI-related software concerns.
- • Lender leverage is improving: more respondents said demand for private credit loans exceeds supply, and a $50M EBITDA non-cyclical business could price a unitranche loan above S+550, though top-quality borrowers still win sub-S+500 pricing.
- • Covenant terms on core middle market direct lending deals are expected to tighten considerably in the coming months, with a less pronounced shift in the lower middle market.
- • Secondary market inventory of private credit loans rose in Q3, and secondary trading appears to be becoming more widespread.
Summary
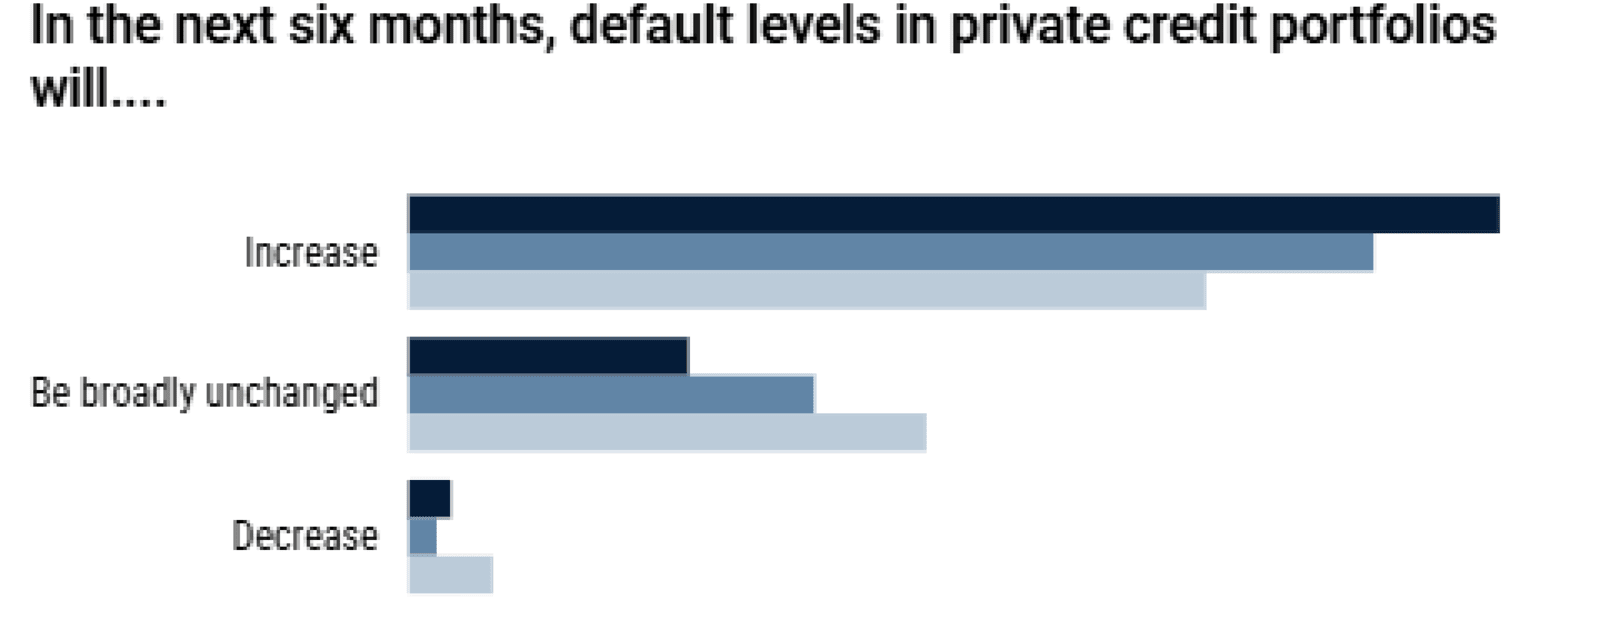
PitchBook LCD's Q3 Global Private Credit Survey indicates that the negative market perception that weighed on private credit through 2026 began to moderate in the third quarter, but concerns over default risk and market stress have intensified. Respondents named default risk and market stress as the greatest challenge facing the asset class over the next six months, a shift from H1 2026, when negative perception ranked first. More respondents also expect default rates in private credit portfolios to rise.
Negative market sentiment remains the second-greatest challenge, reflecting elevated redemptions at non-traded BDCs. PitchBook LCD data show net flows at these vehicles turned negative for the first time in the dataset's history in Q2 2026. A plurality of respondents characterized the outflows as a temporary setback driven by AI-related software concerns rather than a structural problem. Nearly a third expected elevated redemptions to accelerate secondary market development, and more respondents reported that the inventory of private credit loans available on the secondary market grew in Q3.
Dealmaking expectations softened. More respondents anticipated flat or lower deal activity for the remainder of the year, a reversal from earlier expectations for a ramp-up. Respondents attributed the moderation in M&A expectations largely to the Fed's mid-September rate hike. CME FedWatch data cited in the survey put roughly 85% odds on the Fed holding rates steady at its Oct. 28 meeting. Respondents still regarded high PE dry powder and exit needs as the main drivers of an M&A acceleration over the next 12 months, with declining rates and cost of capital ranking second.
The competitive balance has shifted toward lenders. More respondents said loan demand now exceeds supply, reversing 2025 conditions, and PitchBook LCD's Private Credit Monitor shows spreads widening. Some pricing bifurcation persists, however, as high-quality borrowers still obtain sub-S+500 pricing. Respondents expect covenant terms on core middle market direct lending deals to tighten considerably, with a milder tightening in the lower middle market. Valuation concerns were stable overall, with a majority still somewhat worried that valuation pressures could impede refinancing, and a slight uptick in those who were very worried.
Go deeper than the headline
Research every firm in this story, track the ones that matter and get the daily briefing — free for 7 days.