
Key Takeaways
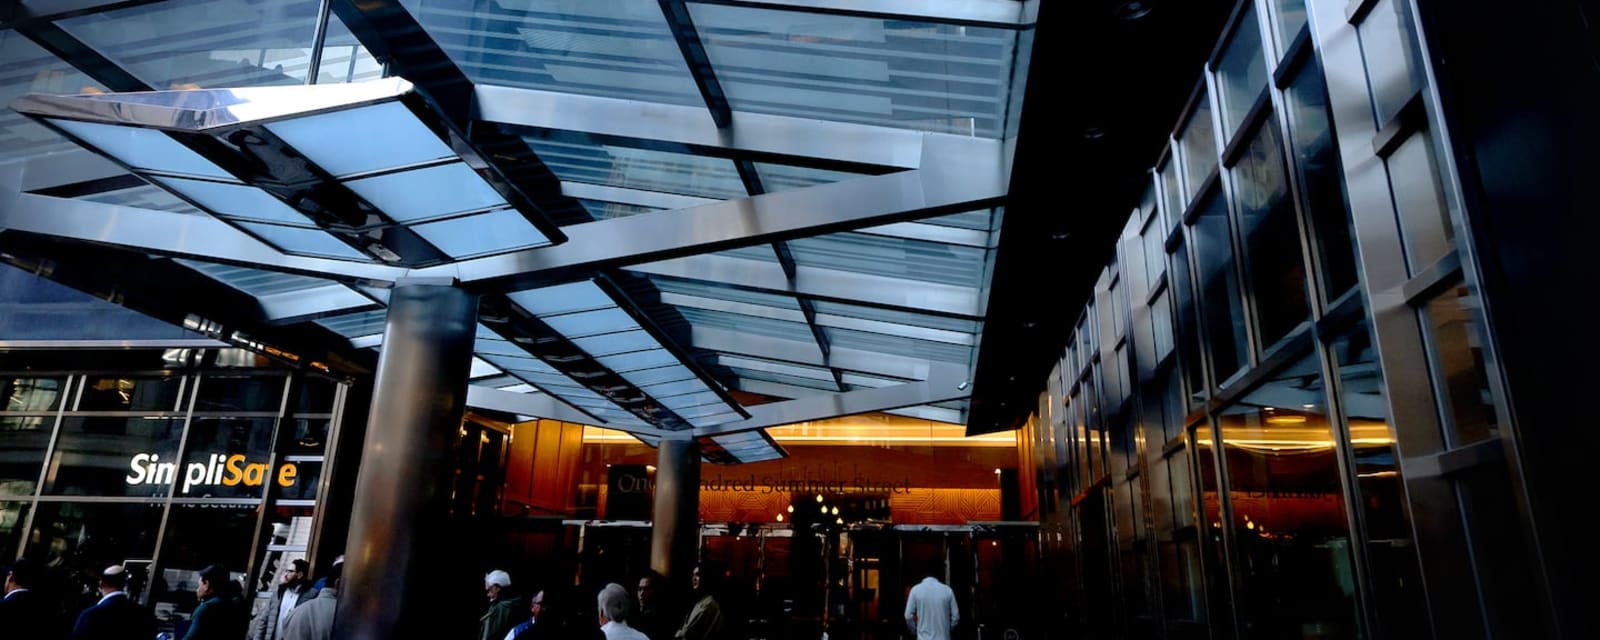
- • Boston-based private equity firm Rockpoint Group repurchased 100 Summer St., a 1.1 million-square-foot downtown Boston office tower, for $260 million at a Wells Fargo-run auction, a 68 percent discount to the $806 million it paid in October 2019.
- • Rockpoint defaulted on its $470 million mortgage loan, which Rockpoint's senior managing director Fred Borges attributed to pandemic-driven declines in office property values rather than the asset's performance.
- • The $260 million price is 39 percent below the building's current assessed value of $425.4 million, according to the Boston Globe report.
- • Hunneman's Mark Fallon called the price "definitely on the very low side" for a downtown skyscraper of that size, while Rockpoint, which manages $13 billion in assets, is funding the purchase with equity and new third-party financing.
- • Rockpoint plans to explore property upgrades, including a possible roof deck, as the Boston office market continues to face value declines that pressure the city's property tax base.
Summary
Boston-based private equity investor Rockpoint Group agreed on a Tuesday to repurchase 100 Summer St., a 1.1 million-square-foot downtown office tower, at a 68 percent discount to its prior cost, according to the Boston Globe. Rockpoint bought the property in October 2019 for $806 million. The firm defaulted on its $470 million mortgage loan, which Wells Fargo financed. The bank then ran an auction, and the winning price was $260 million, which Rockpoint paid using a combination of its own equity and new third-party financing. Rockpoint did not know where the bidding would start, according to Fred Borges, the firm's senior managing director.
Borges said the default was a response to the pandemic's disruption of the office market rather than a judgment on the asset itself. "It had nothing to do with the performance of the asset, or our lack of belief in the future performance of the asset," he said, adding that the value had fallen well below the loan balance. Erik Carlson, a Rockpoint spokesperson, said defaulting and repurchasing distressed properties at steep discounts is not a deliberate business strategy for the firm in Boston or its wider US portfolio. Wells Fargo spokesperson Bryan Darrow declined to comment on the auction, and the deal terms have not yet been formally recorded.
The sale price sits 39 percent below the building's current assessed value of $425.4 million. Mark Fallon, director of research and strategy at the brokerage Hunneman, said the price was "definitely on the very low side" for a downtown skyscraper of more than one million square feet, adding that it was "a great deal for Rockpoint." Manish Srivastava, a real estate finance professor at New York University, described the broader post-pandemic pattern of "extend and pretend," in which lenders and owners work to recover value, and noted that lenders must auction nonperforming loans if negotiations fail.
The transaction comes as Boston's commercial property values continue to decline, a concern for a city that relies on property taxes for nearly three-quarters of its $4.9 billion operating budget. The Globe noted that the sale followed the foreclosure auction of One Lincoln St., another 1.1 million-square-foot tower that sold for far less than its prior owner paid, though that buyer was one of its lenders. Rockpoint, which manages $13 billion in assets, plans to evaluate enhancements to 100 Summer St., and the auction materials flagged potential for a roof deck. The firm previously developed the High Street Place food hall with affiliate Rockhill Management.
Go deeper than the headline
Research every firm in this story, track the ones that matter and get the daily briefing — free for 7 days.