
Key Takeaways
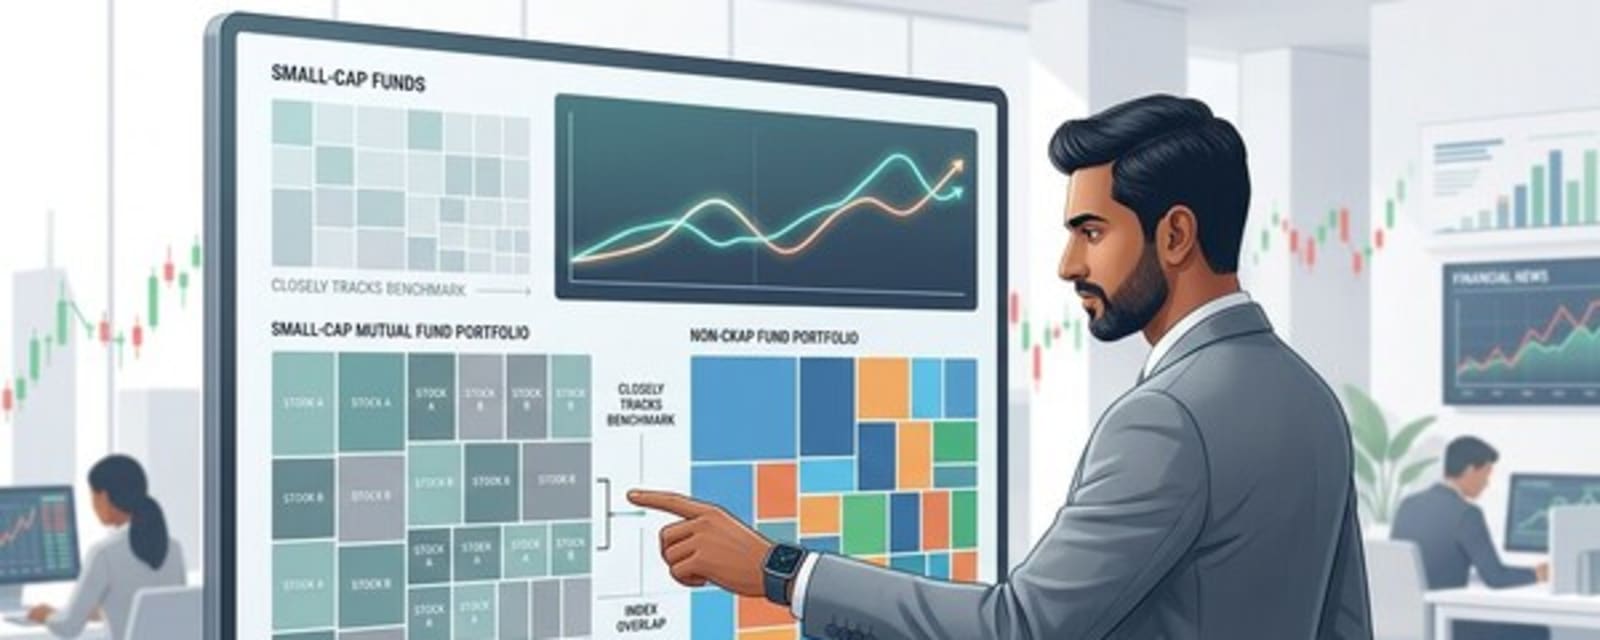
- • Portfolio overlap among small-cap funds ranges from 6.8% to 32.7%, with top-performing funds showing significantly higher benchmark overlap (26.6%–32.7%) compared to bottom-performing funds (6.8%–13.1%), yet this correlation does not guarantee superior returns.
- • Higher benchmark overlap does not automatically translate to better or worse performance, challenging the assumption that active stock selection skill differentiates fund managers from their benchmarks in the small-cap space.
- • Small-cap active managers demonstrate extreme performance dispersion, with 82.2% of managers underperforming their benchmarks over a 10-year period, though this improved dramatically in 2024 when only 29.7% underperformed—indicating cyclical rather than structural outperformance.
- • Funds with benchmark discrepancies (lower overlap) tend to carry higher risk profiles than their prospectus benchmarks indicate, suggesting that managers diverging from benchmarks may be taking concentrated bets that do not consistently compensate investors for the additional risk exposure.
- • Limited research coverage in small-cap markets creates potential for manager outperformance through active stock selection, though structural headwinds from fees and expenses continue to suppress returns for the majority of active managers relative to passive alternatives.
Summary
The relationship between benchmark overlap and active fund performance in the small-cap space remains more complex and less straightforward than investors might assume. Research indicates that small-cap funds tracking the same benchmark exhibit portfolio overlap ranging from 6.8% to 32.7%, creating a natural experiment for evaluating whether higher alignment with benchmark constituents correlates with superior or inferior returns. Notably, top-performing funds maintained overlap levels between 26.6% and 32.7%, while bottom-performing funds showed significantly lower overlap at 6.8% to 13.1%—yet this apparent pattern does not definitively establish causation or a reliable predictive framework for investors.
The critical finding is that elevated benchmark overlap does not automatically produce better outcomes, nor does lower overlap guarantee underperformance. This challenges a core assumption underlying active management: that substantial divergence from benchmarks through concentrated stock selection should yield meaningful alpha. The data suggests that managers cannot reliably exploit small-cap market inefficiencies simply by deviating further from their stated benchmarks, undermining a key narrative for active management fees in this category.
Small-cap active management exhibits pronounced cyclicality in relative performance. Over a 10-year period, 82.2% of small-cap managers underperformed their benchmarks, reflecting persistent headwinds from fees and expenses that weigh on long-term results. However, 2024 produced an anomalous year in which only 29.7% of small-cap managers underperformed, indicating that performance improvement is possible but not consistent. Funds with lower benchmark overlap—those deliberately diverging from their stated benchmarks—tend to carry higher actual risk profiles than their prospectuses indicate, creating a hidden risk-return mismatch that does not consistently compensate investors for the elevated volatility.
The small-cap market structure offers theoretical advantages for active management due to limited analyst coverage and wider performance dispersion between top and bottom performers. However, these structural advantages have not translated into consistent outperformance for the majority of active managers when fees are considered. For institutional investors evaluating small-cap fund allocations, the evidence suggests that benchmark overlap alone is not a reliable indicator of skill or future performance, and that managers with significantly lower overlap may be taking concentrated directional bets rather than executing superior stock selection—a distinction with material implications for portfolio construction and risk management.
Go deeper than the headline
Research every firm in this story, track the ones that matter and get the daily briefing — free for 7 days.