
Key Takeaways
- • Bitcoin experienced a sharp Q2 selloff, declining over 20% to $42,000 from prior levels, yet institutional responses diverged sharply across asset classes and geographies.
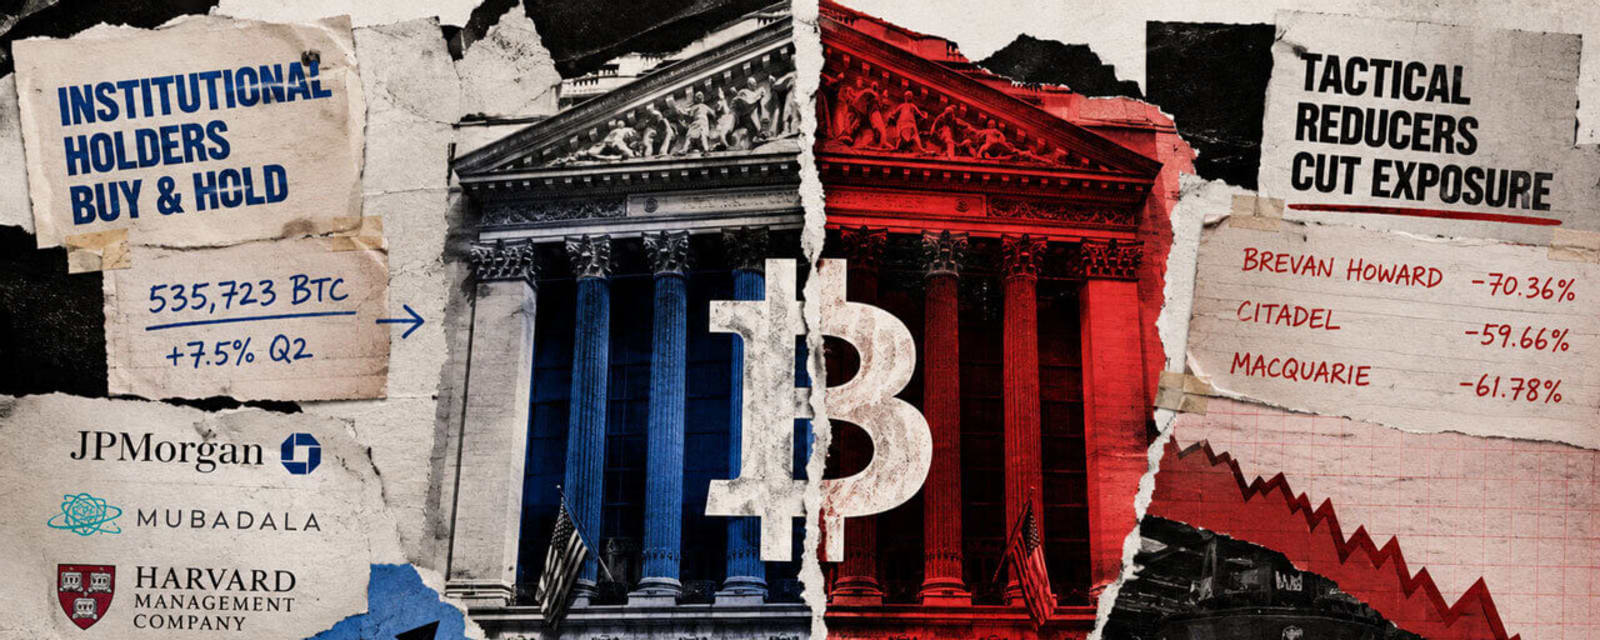
- • Hedge funds aggressively reduced exposure, selling 31,400 BTC in Q1 2026 and cutting holdings by 39%, while major banks including JPMorgan and Wells Fargo increased or maintained Bitcoin ETF positions during the same period.
- • Sovereign wealth funds, including Abu Dhabi, held steady through the volatility, demonstrating a longer-term allocation strategy distinct from both hedge fund liquidations and bank accumulation.
- • Bitcoin's correlation with equities during the selloff contradicted its intended function as an inflation hedge and currency debasement protection, instead falling faster than stocks during risk-off conditions.
- • Q2 13F filings revealed four distinct institutional patterns: sovereign funds held positions, JPMorgan added shares, UBS shifted to options strategies, and Morgan Stanley added Bitcoin trust holdings.
Summary
Bitcoin's second-quarter decline exposed a fundamental fracture in institutional investor conviction. The cryptocurrency plummeted over 20% to $42,000—sharply lower than its prior level of $49,200—yet institutional responses fragmented across distinct investor categories, undermining the narrative of coordinated Wall Street adoption.
Hedge funds led the retreat. Q1 2026 filings revealed liquidations of 31,400 BTC held in spot Bitcoin ETFs, representing a 39% reduction in hedge fund holdings. This aggressive de-risking suggested that despite Bitcoin's prominence in allocator conversations, short-term performance pressure and correlation with equities triggered rapid position trimming. The hedge fund exodus stood in stark contrast to their anticipated role as long-term alternative asset stewards.
Commercial banks adopted the opposite posture. JPMorgan, Wells Fargo, and other major financial institutions increased or maintained Bitcoin ETF holdings during the same drawdown period, signaling conviction in longer-dated accumulation strategies despite near-term volatility. This bank-led buying during weakness reflected institutional strategies calibrated to multi-year time horizons rather than quarterly performance benchmarks.
Sovereign wealth funds, particularly Abu Dhabi's sovereign allocators, neither capitulated nor aggressively added, instead holding positions steady. This measured response highlighted sovereign investors' structural difference from both hedge funds and banks—exemption from quarterly redemption pressure and performance mandates allowed sovereigns to view Bitcoin drawdowns as temporary rather than portfolio warning signals.
The Q2 bifurcation highlighted a critical vulnerability in Bitcoin's institutional thesis: its correlation with equities during the selloff contradicted the asset's positioning as an inflation hedge and currency debasement protection. Bitcoin fell faster than stocks during risk-off conditions, undermining the diversification rationale that justified initial Wall Street entry. This dislocation between Bitcoin's marketed role and its demonstrated market behavior created the fragmented institutional response evident in 13F filings, where different investor archetypes pursued incompatible strategies within the same asset class.
Hedge funds led the retreat. Q1 2026 filings revealed liquidations of 31,400 BTC held in spot Bitcoin ETFs, representing a 39% reduction in hedge fund holdings. This aggressive de-risking suggested that despite Bitcoin's prominence in allocator conversations, short-term performance pressure and correlation with equities triggered rapid position trimming. The hedge fund exodus stood in stark contrast to their anticipated role as long-term alternative asset stewards.
Commercial banks adopted the opposite posture. JPMorgan, Wells Fargo, and other major financial institutions increased or maintained Bitcoin ETF holdings during the same drawdown period, signaling conviction in longer-dated accumulation strategies despite near-term volatility. This bank-led buying during weakness reflected institutional strategies calibrated to multi-year time horizons rather than quarterly performance benchmarks.
Sovereign wealth funds, particularly Abu Dhabi's sovereign allocators, neither capitulated nor aggressively added, instead holding positions steady. This measured response highlighted sovereign investors' structural difference from both hedge funds and banks—exemption from quarterly redemption pressure and performance mandates allowed sovereigns to view Bitcoin drawdowns as temporary rather than portfolio warning signals.
The Q2 bifurcation highlighted a critical vulnerability in Bitcoin's institutional thesis: its correlation with equities during the selloff contradicted the asset's positioning as an inflation hedge and currency debasement protection. Bitcoin fell faster than stocks during risk-off conditions, undermining the diversification rationale that justified initial Wall Street entry. This dislocation between Bitcoin's marketed role and its demonstrated market behavior created the fragmented institutional response evident in 13F filings, where different investor archetypes pursued incompatible strategies within the same asset class.
Go deeper than the headline
Research every firm in this story, track the ones that matter and get the daily briefing — free for 7 days.