
Key Takeaways
- • Bitcoin accumulation at $60K–$70K price levels signals institutional positioning, but conviction remains thin as market participants adopt a wait-and-see posture ahead of macroeconomic catalysts.
- • Upcoming US CPI data and scheduled Iran–US peace talks this weekend are the dominant market drivers, with positioning compressed across crypto, metals, and broader risk assets pending these macro events.
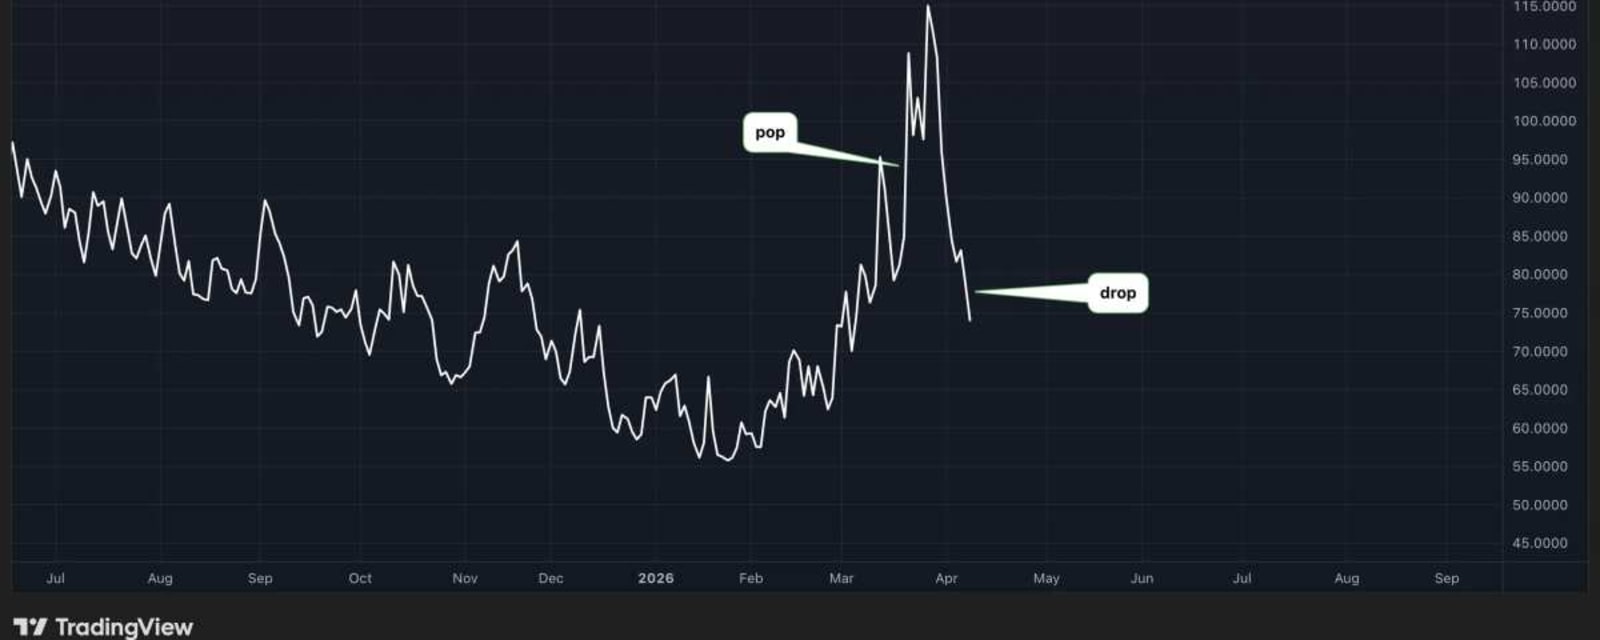
- • Oil markets (Brent crude trading near $97/barrel) remain vulnerable to negotiation outcomes; failure to achieve at least a Strait of Hormuz reopening agreement could trigger significant risk-off rotation and commodity repricing.
- • European equities rallied Friday on peace-talk optimism—bucking a month-long pattern of end-of-week risk reduction—while the S&P 500 and Nasdaq are tracking strong weekly gains (3.7% and 4.5% respectively), contingent on deal progress and benign inflation data.
- • Real yields and Fed expectations remain the transmission channel governing asset positioning; market participants have shifted from directional conviction to tactical calibration ahead of the CPI release.
Summary
Institutional Bitcoin positioning exhibits a cautious, non-committal stance entering a critical week dominated by two major catalysts: the US CPI release and Iran–US peace negotiations scheduled for the weekend. According to market analysis from the Crypto Daybook, Bitcoin buyers have accumulated approximately 850,000 BTC within the $60K–$70K range, but the thinner accumulation above $70,000 suggests limited institutional conviction and signals potential for heightened volatility as price discovery attempts to establish new levels.
The macro environment is bifurcated. Peace talks between Iran and the US have prompted a tactical risk-on reorientation in equity markets, with European indices posting gains and US indices (S&P 500 up 3.7%, Nasdaq up 4.5% on the week) staging their strongest performance in recent weeks. However, the optimism is fragile and conditional. While Brent crude has declined over 10% this week—its steepest loss in nine months—crude still trades near $97 per barrel, vulnerable to rapid reversal if negotiations falter. Key outcomes being priced in include a reopening of the Strait of Hormuz to ensure safe tanker passage; absent this accord, traders anticipate significant risk aversion and oil price surges early the following week.
Across commodities and financial markets, positioning has compressed sharply ahead of the CPI data release. Silver, for example, trades near the upper band of its structure (76.50 regime pivot, 77.30–77.45 ceiling) with market participants reducing directional exposure while maintaining sensitivity to inflation messaging. Real yields and Fed expectations remain the dominant transmission channel; participants have shifted from extension (directional conviction) to calibration (tactical hedging), with limited range reflecting preparation rather than commitment.
The market structure reflects a system in equilibrium pending resolution of these twin shocks. The ceasefire remains fragile—President Trump has condemned Iran for not reopening the Strait, while Iran has demanded reparations—suggesting that negotiations may involve protracted brinkmanship before yielding concrete outcomes. Nevertheless, traders are looking through near-term posturing toward substantive negotiations. The combination of dormant institutional conviction in crypto, compressed positioning across metals and rates, and equity market gains predicated on peace-talk progress creates a brittle setup where both CPI data and diplomatic outcomes will likely trigger sharp reallocation of risk capital across asset classes.
The macro environment is bifurcated. Peace talks between Iran and the US have prompted a tactical risk-on reorientation in equity markets, with European indices posting gains and US indices (S&P 500 up 3.7%, Nasdaq up 4.5% on the week) staging their strongest performance in recent weeks. However, the optimism is fragile and conditional. While Brent crude has declined over 10% this week—its steepest loss in nine months—crude still trades near $97 per barrel, vulnerable to rapid reversal if negotiations falter. Key outcomes being priced in include a reopening of the Strait of Hormuz to ensure safe tanker passage; absent this accord, traders anticipate significant risk aversion and oil price surges early the following week.
Across commodities and financial markets, positioning has compressed sharply ahead of the CPI data release. Silver, for example, trades near the upper band of its structure (76.50 regime pivot, 77.30–77.45 ceiling) with market participants reducing directional exposure while maintaining sensitivity to inflation messaging. Real yields and Fed expectations remain the dominant transmission channel; participants have shifted from extension (directional conviction) to calibration (tactical hedging), with limited range reflecting preparation rather than commitment.
The market structure reflects a system in equilibrium pending resolution of these twin shocks. The ceasefire remains fragile—President Trump has condemned Iran for not reopening the Strait, while Iran has demanded reparations—suggesting that negotiations may involve protracted brinkmanship before yielding concrete outcomes. Nevertheless, traders are looking through near-term posturing toward substantive negotiations. The combination of dormant institutional conviction in crypto, compressed positioning across metals and rates, and equity market gains predicated on peace-talk progress creates a brittle setup where both CPI data and diplomatic outcomes will likely trigger sharp reallocation of risk capital across asset classes.
Go deeper than the headline
Research every firm in this story, track the ones that matter and get the daily briefing — free for 7 days.