
Key Takeaways
- • Mott Capital's Mike Kramer expects a Monday volatility-driven bounce in the S&P 500 that is unlikely to last beyond that day, as liquidity pressures from Treasury issuance weigh on the holiday-shortened week.
- • The 1-day VIX climbed to 51 on Friday, and Kramer sees a likely volatility crush on Monday, though implied volatility is expected to rise again ahead of the October PCE report on Wednesday.
- • Treasury settlements total $51.3 billion on Tuesday and $28 billion in coupon securities plus $16.6 billion in Treasury bills on November 27, with net issuance expected to keep rising through the week of December 7.
- • October headline PCE is expected at +0.3% month over month and 3.8% year over year, while core PCE is expected at +0.3% month over month and 3.2% year over year.
- • Bitcoin is testing a break below $60,000 with downside risk toward $54,000, according to the author.
Summary
The S&P 500 faces a shortened holiday trading week following a sharp sell-off the prior week, according to market commentary from Mike Kramer of Mott Capital Management. The week's central event is the October Personal Consumption Expenditures (PCE) report on Wednesday. Headline PCE is expected to rise 0.3% month over month, down from 0.5% in September, and 3.8% year over year, up from 3.6%. Core PCE is expected to rise 0.3% month over month, matching September, and 3.2% year over year, up from 3.1%.
Treasury supply adds to the pressure. Kramer cites $51.3 billion in settlements on Tuesday, followed by $28 billion in coupon securities and $16.6 billion in Treasury bills on November 27. He expects net issuance to continue rising through the week of December 7, which he argues will weigh on risk assets. Bitcoin has already reflected this pressure, testing a break below $60,000 with the risk of a decline toward $54,000.
Kramer notes that heavy Treasury issuance has coincided with rising implied volatility, and the 1-day VIX reached 51 on Friday. He argues that the shortened week could produce a volatility crush on Monday, as implied volatility falls sharply and may support a stock rally. He questions whether these mechanical forces can outweigh liquidity pressures, and he expects implied volatility to climb again on Tuesday ahead of the PCE report, making any Monday relief likely short-lived.
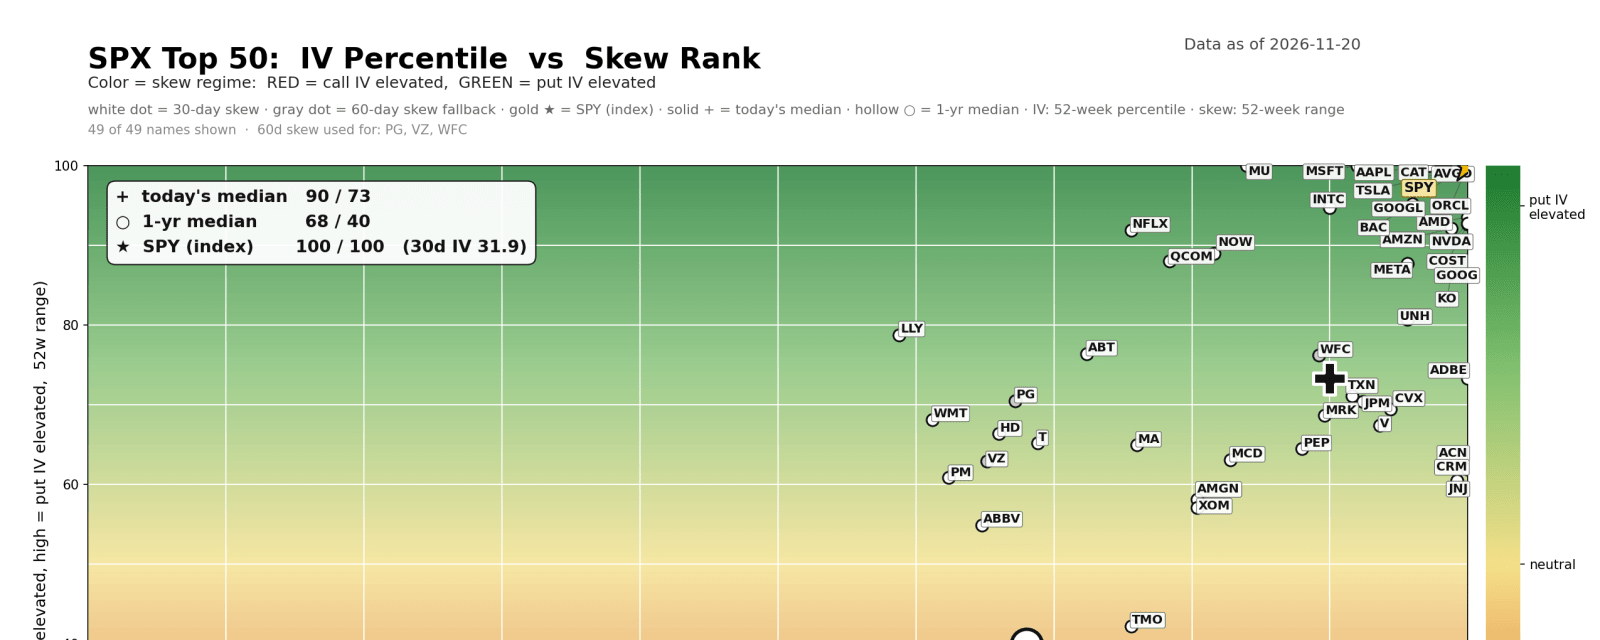
Kramer also describes positioning as stretched. He points to a heat map of implied volatility and skew showing the top 50 S&P 500 stocks clustered in the upper-left corner, which he interprets as the options market being about as bearish as it can get. He adds that with both the VIX and realized volatility elevated, volatility sellers are unlikely to step in aggressively, and CTA positioning suggests systematic sellers may add pressure. His base case is that Monday's bounce fades and the rest of the week becomes a contest between liquidity pressures and mechanical forces.
Treasury supply adds to the pressure. Kramer cites $51.3 billion in settlements on Tuesday, followed by $28 billion in coupon securities and $16.6 billion in Treasury bills on November 27. He expects net issuance to continue rising through the week of December 7, which he argues will weigh on risk assets. Bitcoin has already reflected this pressure, testing a break below $60,000 with the risk of a decline toward $54,000.
Kramer notes that heavy Treasury issuance has coincided with rising implied volatility, and the 1-day VIX reached 51 on Friday. He argues that the shortened week could produce a volatility crush on Monday, as implied volatility falls sharply and may support a stock rally. He questions whether these mechanical forces can outweigh liquidity pressures, and he expects implied volatility to climb again on Tuesday ahead of the PCE report, making any Monday relief likely short-lived.
Kramer also describes positioning as stretched. He points to a heat map of implied volatility and skew showing the top 50 S&P 500 stocks clustered in the upper-left corner, which he interprets as the options market being about as bearish as it can get. He adds that with both the VIX and realized volatility elevated, volatility sellers are unlikely to step in aggressively, and CTA positioning suggests systematic sellers may add pressure. His base case is that Monday's bounce fades and the rest of the week becomes a contest between liquidity pressures and mechanical forces.
Go deeper than the headline
Research every firm in this story, track the ones that matter and get the daily briefing — free for 7 days.