
Key Takeaways
- • European private equity and venture capital aerospace and defense deal value surged 4.8x year-over-year to $658.8 million in 2025, reaching its highest level since 2022 when Russia's invasion of Ukraine catalyzed defense spending across the continent.
- • Global aerospace and defense PE/VC investment more than doubled to $10.63 billion in 2025 from $4.88 billion in 2024, with US-based managers targeting European defense opportunities at four-year highs alongside healthcare and infrastructure.
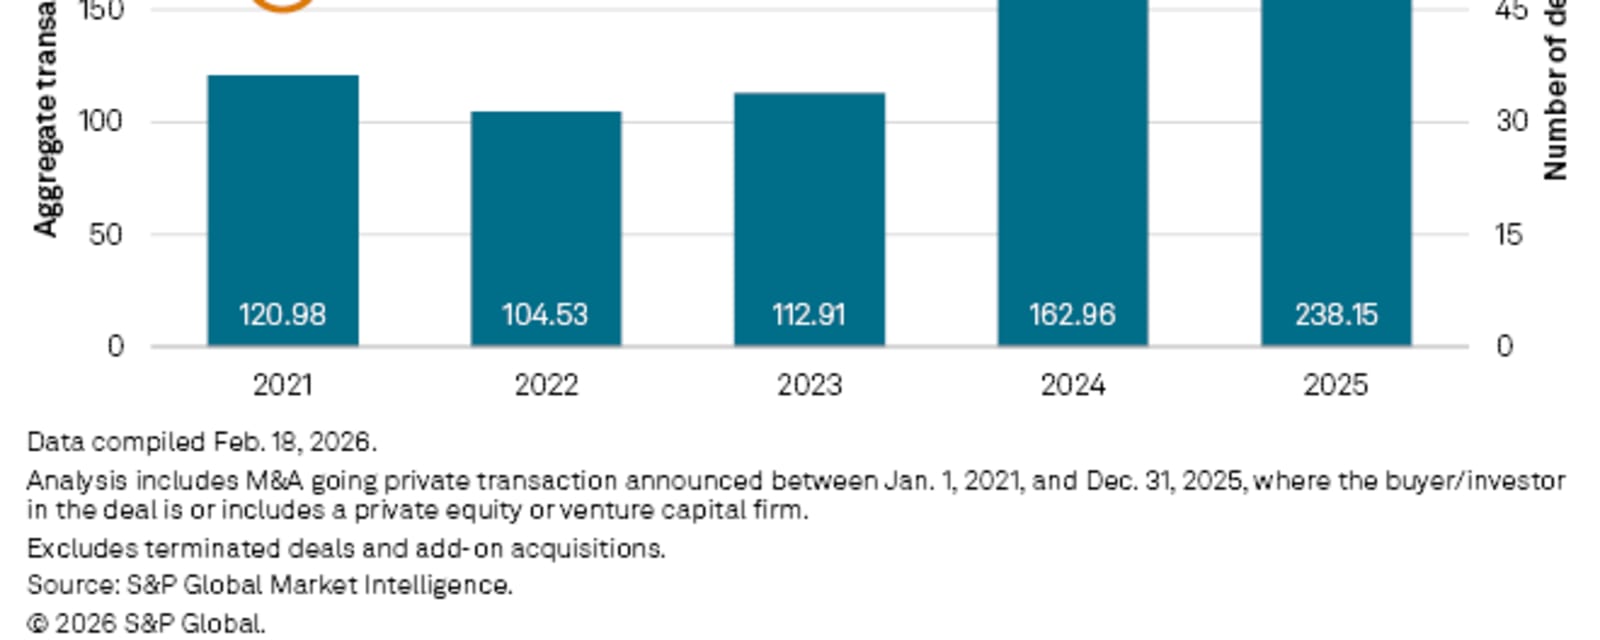
- • Take-private deal volume backed by private equity and venture capital climbed 46.1% year-over-year to $238.15 billion in 2025, driven by landmark transactions including the $55 billion Electronic Arts acquisition by Public Investment Fund, Silver Lake Technology Management, and A Fin Management announced in September 2025.
- • UK regulators are witnessing the launch of new private equity funds specifically structured to overcome historical fund rules that prevented defense sector investment, signaling institutional repositioning around geopolitical security priorities.
Summary
Private equity capital is flooding European defense and aerospace assets at unprecedented velocity, with 2025 marking a decisive inflection point for the sector across both established and emerging fund structures. According to S&P Global Market Intelligence, European and UK aerospace and defense deal value jumped to $658.8 million in 2025—a 4.8x increase year-over-year and the highest total recorded since 2022, when Russia's military invasion of Ukraine triggered sustained defense spending acceleration across NATO and allied nations.
The momentum reflects a broader institutional awakening to defense as a core alternative investment thesis. Global private equity and venture capital aerospace and defense investments more than doubled to $10.63 billion in 2025 from $4.88 billion in 2024. Notably, US-based managers have elevated defense alongside healthcare and infrastructure as top deployment targets in 2025, with aggregate US fund investments in European defense reaching four-year highs. This signals that American capital is actively arbitraging geopolitical risk premiums and supply chain consolidation opportunities across the Atlantic.
Regulatory barriers are dissolving as market demand intensifies. In the UK, where historical fund restrictions limited defense sector participation by certain private equity vehicles, new funds are being launched specifically to capture this opening, according to Dafydd Evans, managing director in Kroll LLC's investment banking practice. This structural adaptation underscores how policy constraints are being actively circumvented as LPs and GPs reprioritize defense as a legitimate and strategically essential asset class amid heightened geopolitical tensions.
The broader take-private market also reached inflection velocity in 2025, with sponsor-backed take-private deal value climbing 46.1% year-over-year to $238.15 billion. This surge was heavily weighted by the largest sponsor-backed take-private transaction on record—Electronic Arts Inc.'s pending $55 billion acquisition by Public Investment Fund, Silver Lake Technology Management, and A Fin Management, announced in September 2025. While not exclusively a defense play, this mega-deal illustrated the scale and conviction with which alternative capital is moving into strategic sectors.
The European defense build-out represents a structural, multi-decade capital redeployment cycle driven by geopolitical necessity rather than cyclical opportunity. With defense budgets now permanently elevated across the continent, private equity positioning in aerospace and defense contractors, supply chain consolidators, and dual-use technology platforms has shifted from niche tactical allocation to core institutional positioning.
Go deeper than the headline
Research every firm in this story, track the ones that matter and get the daily briefing — free for 7 days.