
Key Takeaways
- • Cap rate compression expectations are moderating in 2026: CBRE forecasts cap rates will compress by only 5 to 15 basis points across most property types, a significant departure from the extended period of aggressive valuation repricing that characterized the prior decade.
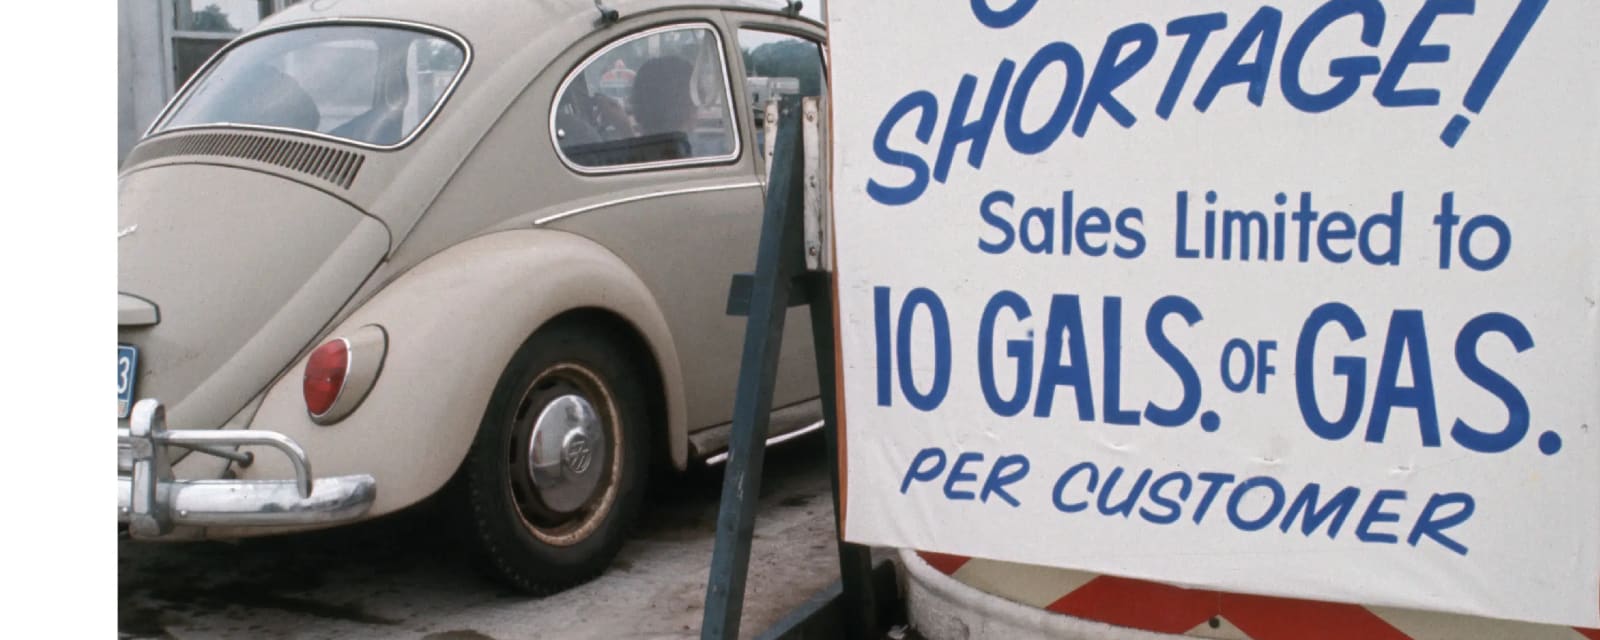
- • Macroeconomic parallels to the 1970s are reshaping investment frameworks: Hines research identifies structural similarities between today's environment (energy-fueled inflation, geopolitical volatility, constrained monetary policy) and the 1970s, challenging the assumption that declining interest rates will drive returns as they did throughout the 1980s-2020s period.
- • Income durability, not valuation expansion, is becoming the primary return driver: Investors are shifting emphasis toward cash flow sustainability and disciplined underwriting, with cap rates now reflecting normalized interest rate environments and reduced reliance on financial leverage as the dominant source of returns.
- • Interest rates, job/income growth, and inflation are the top three macro concerns for real estate in 2026: PwC and industry leaders identify these factors as critical determinants of cap rate behavior, with elevated operating costs (insurance, labor, maintenance) persisting despite moderated inflation expectations.
- • Fundamental repricing has realigned asset values with long-term fundamentals: After reduced transaction activity and valuation corrections, 2026 marks a shift toward pricing discipline increasingly aligned with cash flow generation capacity rather than short-term capital market distortions.
Summary
The commercial real estate market in 2026 is operating within a fundamentally altered macroeconomic framework that challenges decades of assumptions about cap rate behavior and value creation. According to Hines research published in April 2026, the parallels between today's inflation-driven environment and the 1970s period—characterized by energy-fueled inflation, geopolitical instability, and constrained monetary policy—are forcing investors to reconsider long-held paradigms about how cap rates move and how returns are generated in real assets.
The critical distinction centers on the underlying drivers of historical returns. Modern real assets research is largely built on data beginning in the early 1980s, coinciding with peak nominal interest rates and the onset of a four-decade disinflationary cycle. During this period, declining discount rates and cap rate compression became the dominant source of value creation. Today's environment, however, presents a different reality: as inflation proves less transitory and monetary policy remains constrained by competing objectives, investors face a scenario where cap rates may not compress at all, placing the burden of returns on income generation rather than valuation expansion.
Current market indicators support this thesis. CBRE's 2026 forecast projects cap rate compression of only 5 to 15 basis points across most property types—a modest adjustment compared to historical norms. Meanwhile, according to PwC and industry leaders, interest rates, job/income growth, and inflation rank as the top three macroeconomic concerns for real estate. Operating cost pressures, particularly in insurance, labor, and maintenance, remain elevated despite moderated inflation expectations, directly impacting property-level income durability. Interest rates continue to anchor cap rate expectations, with investors now demanding higher unlevered returns to compensate for the opportunity cost of capital in a normalized rate environment.
The market has undergone substantial repricing over the preceding years, characterized by reduced transaction volume and significant valuation corrections. As of 2026, however, pricing is increasingly aligned with long-term fundamentals rather than short-term capital market distortions. This disciplined underwriting approach reflects a shift away from leverage-dependent return strategies toward sustainable income streams. For institutional investors and hedge fund managers, the implication is clear: the era of cap rate compression-driven returns has likely ended, replaced by an environment where income stability, operational execution, and disciplined capital allocation will determine competitive positioning in commercial real estate.
Go deeper than the headline
Research every firm in this story, track the ones that matter and get the daily briefing — free for 7 days.